Reverse mortgage rates, and what they actually cost you
We do not publish a rate on this page, and you should be wary of pages that do. Reverse mortgage rates move with the bond market and with each lender's pricing, and a number posted here in one quarter is wrong by the next.
What does not change is how the pricing works. Understand that and you can judge any quote you are given, from us or from anyone else.
Call and we will tell you today's rates from the lenders we work with, out loud, with no form to fill in.
Start with this
Why the rate is higher than a normal mortgage
It is not a penalty for being older, and it is not a markup because the borrower is assumed not to shop around. There is an actual mechanism, and it is worth understanding before you decide whether the trade is fair.
The lender waits, and waiting costs money
On an ordinary mortgage the lender receives a payment every month and can lend that money out again. On a reverse mortgage it receives nothing until the home is sold, which might be in eighteen months or in twenty-five years. Nobody knows which. The lender is funding a loan of unknown length with no cash coming back, and the rate reflects that.
The lender carries the risk that the debt outgrows the house
Because the interest compounds unpaid, the balance climbs while the house may not. Canadian reverse mortgages generally guarantee the estate will never owe more than the home sells for, which means the lender absorbs the shortfall if that happens. That guarantee is genuinely valuable to you, and it is priced into the rate you pay.
There is no income or credit qualification doing the work
On a conventional mortgage your income and credit history carry much of the lender's comfort. Here they largely do not. The security is the house and your age, which is a thinner cushion, and thinner cushions cost more.
So compare it against your real alternative, not against a five-year fixed
Comparing a reverse mortgage rate to a posted bank mortgage rate is comparing two products you cannot both have. If you qualify for a secured line of credit and can service the payments, take it, and we will say so. The reverse mortgage rate is only worth paying when the cheaper options are closed to you. That comparison is set out here.
The choice you will be offered
Fixed or variable, and how the term length changes things
Reverse mortgages come with terms in much the same way ordinary mortgages do, and the term you pick has consequences that go well beyond the rate on the page.
Fixed rate, longer term
The rate is locked for the term. Predictable, and you can model what the balance will look like in ten years. The cost of that certainty is a higher starting rate and, usually, a stiffer penalty if you exit early. Suits someone confident they are staying put.
Fixed rate, shorter term
Lower rate than the long fixed, and you reach a renewal sooner, which is an opportunity to move lenders or repay without penalty. The risk is renewing into a higher rate environment. Often the sensible middle.
Variable rate
Moves with the lender's prime. Usually the lowest starting rate and much the gentlest to get out of, which matters more here than most people realise. The balance grows faster if rates climb, and you cannot forecast the estate position with any precision.
What we look at to choose
How likely you are to move or sell inside five years, whether certainty about the estate matters to you, and whether you are taking one lump sum or drawing over time. Those three answers usually settle it before the rates are even compared.
Want today's actual numbers? We will quote the current rates from the lenders we are approved with, tell you which term we would recommend for your situation and why, and put nothing in writing until you ask us to.
Call 1-416-878-9448The part nobody advertises
The penalty usually costs more than the rate
This is the single most important paragraph on the page, so it gets its own section. Most reverse mortgages end before their term does, because the home sells or the owner moves into care. What happens at that moment is decided by the prepayment clause, not by the interest rate.
The penalty is often a declining schedule
Typically the charge is heaviest in the first year or two and falls away over the term, sometimes to nothing near renewal. Two lenders quoting a similar rate can be thousands of dollars apart in year three. The structure of that schedule is a term you can compare and should.
Some exits are waived, and which ones varies
Many reverse mortgages reduce or waive the penalty when the loan ends because the last borrower has died, and some do the same on a permanent move into long-term care. Not all of them, and not on the same conditions. For an eighty-year-old couple this clause is worth more attention than a quarter point on the rate.
Partial prepayments may be allowed, within limits
Several lenders let you pay down some of the balance each year without penalty, which is a way of controlling the compounding if your circumstances improve. The allowance differs by lender and by product, and it is easy to miss because nobody markets it.
What we do about it
We read the prepayment clause of any commitment before recommending it, and we tell you what leaving early would cost in year one, year three and year five. If the lender with the better rate has the worse exit and you might move, we will recommend the other one. How we compare lenders is here.
What compounding does
How the balance grows when you make no payments
No monthly payment is the appeal of this product and the cost of it. Both things are true and you should hold them at the same time.
Interest is added to the balance, then earns interest itself
Because nothing is paid monthly, each period's interest joins the principal and the next period's interest is calculated on the larger figure. The balance rises more steeply the longer the loan runs. Over a long hold this is the dominant cost, far more than any difference between one lender's rate and another's.
Your equity is a race between two numbers
The debt compounds upward. The house may appreciate, stall or fall. Whether equity remains at the end depends on which moves faster, and nobody can promise you an answer. In long periods of rising Ontario house prices borrowers have often finished with substantial equity intact. That is history, not a forecast, and we will not present it as one.
Taking less, or taking it later, costs much less
Interest only accrues on money actually advanced. Drawing a smaller amount, or taking scheduled advances over the years instead of one lump sum at the start, can change the ten-year balance dramatically. Borrow what you need, not what you qualify for. It is the single most effective thing you can do to control the cost of this product.
Ask to see the projection before you sign
Any competent agent can show you the projected balance at five, ten and fifteen years at the quoted rate. If nobody has offered you one, ask. If the figure at year fifteen makes you uncomfortable, that discomfort is useful information and you should act on it.
Independent reading on costs, from a source with nothing to sell: the Financial Consumer Agency of Canada on reverse mortgages. See also our own breakdown of the setup costs and fees, which are separate from the interest rate.
Who you are dealing with
The people who train the industry on this product
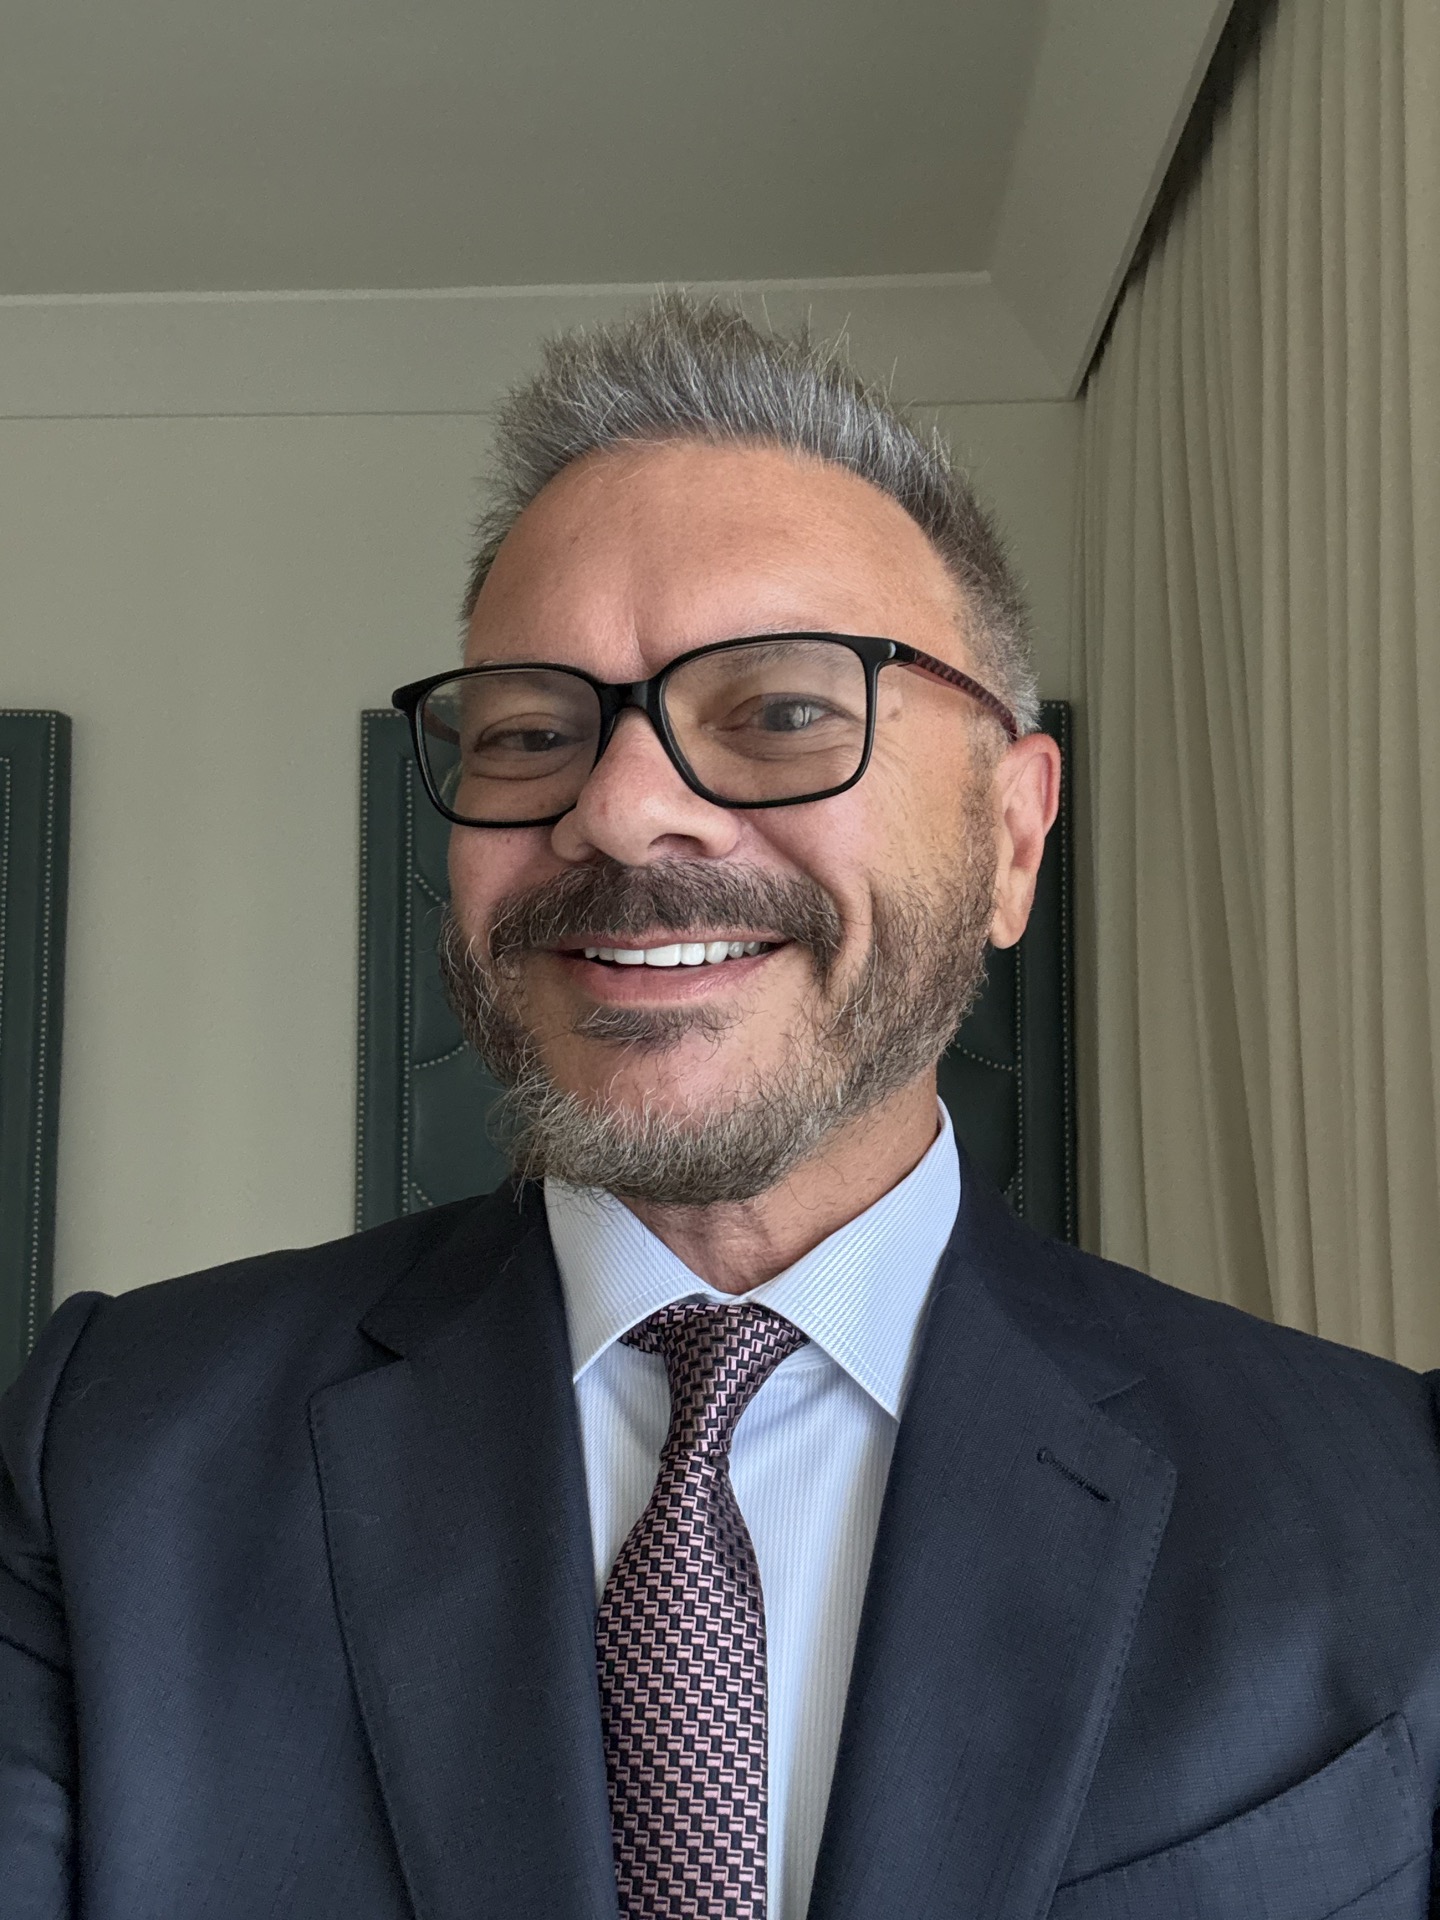
Joe White, principal
Reverse Mortgages of Canada is the reverse mortgage practice of 360 Lending Solutions, led by Joe White.
Joe has spent nearly thirty years in the Canadian mortgage industry. He founded REMIC, the Real Estate and Mortgage Institute of Canada, the country's largest mortgage and insurance education company, and he wrote the Ontario mortgage agent licensing textbook now in its sixteenth edition. If you deal with a licensed mortgage agent in Ontario, there is a good chance they studied from a book he wrote. He was inducted into the Canadian Mortgage Hall of Fame in 2019.
That matters here for one practical reason. Most people arranging reverse mortgages sell one product. We teach the whole subject, including the parts that do not flatter it, which is why you will get a recommendation against this product when it is not the right fit.
At a glance
How much could you unlock from your home?
A quick estimate of the tax-free cash a reverse mortgage could release, based on the four things that move the number most. It gives you a range, not a promise — the exact figure comes from an appraisal and a conversation.
About the home and the homeowners
Four questions. Nothing here identifies you.
If two people own the home, enter the younger age. Lenders price against whoever is expected to live there longest, so a couple usually qualifies for less than the older partner would alone. It is the most commonly misunderstood part of this product.
Your own estimate is fine at this stage.
Location changes this more than most people expect — the same home can be worth tens of thousands more or less depending only on the community.
$0–$0
What moved your estimate
Get the real number
A licensed agent at 360 Lending Solutions will run your actual address, ages and property details and send you the exact figure.
This is an estimate, not an offer of credit. The figures shown are indicative only, produced from a simplified model, and are not a quote, a pre-approval, or a commitment to lend. Actual amounts depend on a full application, a property appraisal, and the lender's criteria and rates on the day. Amounts are rounded.
Reverse mortgages are available to homeowners aged 55 and over. Interest accrues on the outstanding balance and reduces the equity remaining in the home. Independent legal advice is required before completion.
Get today's rates, spoken plainly
We will tell you the current rates from the lenders we work with, what the penalty looks like on each, and which one we would put you with. No form, no application, no obligation.