Is a reverse mortgage a good idea?
Sometimes. Often not. It depends almost entirely on what your alternatives are, and most pages on this subject will not tell you that because they only sell the one product.
We train mortgage agents on this for a living, including the parts that do not flatter it. Here is the version we teach.
Asking on behalf of a parent? That is who half these calls come from.
The short answer
When it is the wrong answer
Start here rather than at the end, because if any of these apply, the rest does not matter much.
If you can afford the payments on something cheaper
A conventional mortgage or a secured line of credit almost always costs less. A reverse mortgage earns its place when the monthly payment on those options is the problem, not when it is merely inconvenient. If your income services a conventional loan, take the conventional loan.
If the home is likely to sell within a couple of years
Setup costs, appraisal and legal fees are the same whether the loan runs two years or twenty. Over a short horizon they rarely justify themselves. If a move is coming, a bridge or a short-term solution usually beats this.
If someone else is doing the asking
If an adult child, a caregiver or anyone else is the one pushing an elderly owner to release cash, we slow down and involve the lawyer early. That is not a judgement about your family. It is the single most common way this product gets misused, and the independent legal advice requirement exists precisely for it.
The honest comparison
How it stacks up against the alternatives
Four ways to get at the money in a home after 55, and what each one actually costs you.
Secured line of credit
Cheapest rate of the four. Requires income to qualify and monthly interest payments. If you can get one and service it, this usually wins. Many people over 70 no longer qualify on income, which is where the conversation tends to start.
Conventional mortgage
Cheaper than a reverse mortgage. Same qualifying problem: it is underwritten on your income, and retirement income often does not support the payment even when substantial equity exists.
Selling and downsizing
Releases the most money and carries no interest at all. It also costs you the home, the neighbourhood, and roughly five percent in transaction costs. For many people the whole point is staying put, which is a legitimate reason to pay more.
Reverse mortgage
Highest rate, no payments, no income qualification, and you stay in the home. The equity shrinks over time because the interest compounds. It is the right answer when the alternatives are blocked, and the expensive answer when they are not.
Advising a parent or a client? Send us the ages, the property type and the community, and we will tell you what is realistically available and whether we think it is the right move. No client contact unless you ask for it.
Call 1-416-878-9448The other questions
The three things families ask next
Can the lender take the home?
No. You keep the title. The lender registers a charge against the property the same way a bank does with an ordinary mortgage. You agree to keep it as your principal residence, keep the taxes and insurance paid, and keep it in reasonable repair. The loan becomes repayable when the last homeowner sells, moves out permanently, or passes away.
What does it do to the inheritance?
It reduces it, and there is no honest way to say otherwise. What it does not do is create a debt the estate cannot cover. These products in Canada generally guarantee that the estate will never owe more than the fair market value of the home at sale, provided the terms were met. Confirm that guarantee is in the specific contract, and we will show you where it appears.
Does it affect OAS or GIS?
No. The proceeds are loan advances, not income. They are not taxable and they do not enter net income for income-tested benefits. For someone near an OAS clawback threshold, that is often the entire reason this option is being considered instead of drawing down a RRIF.
Who you are dealing with
The people who train the industry on this product
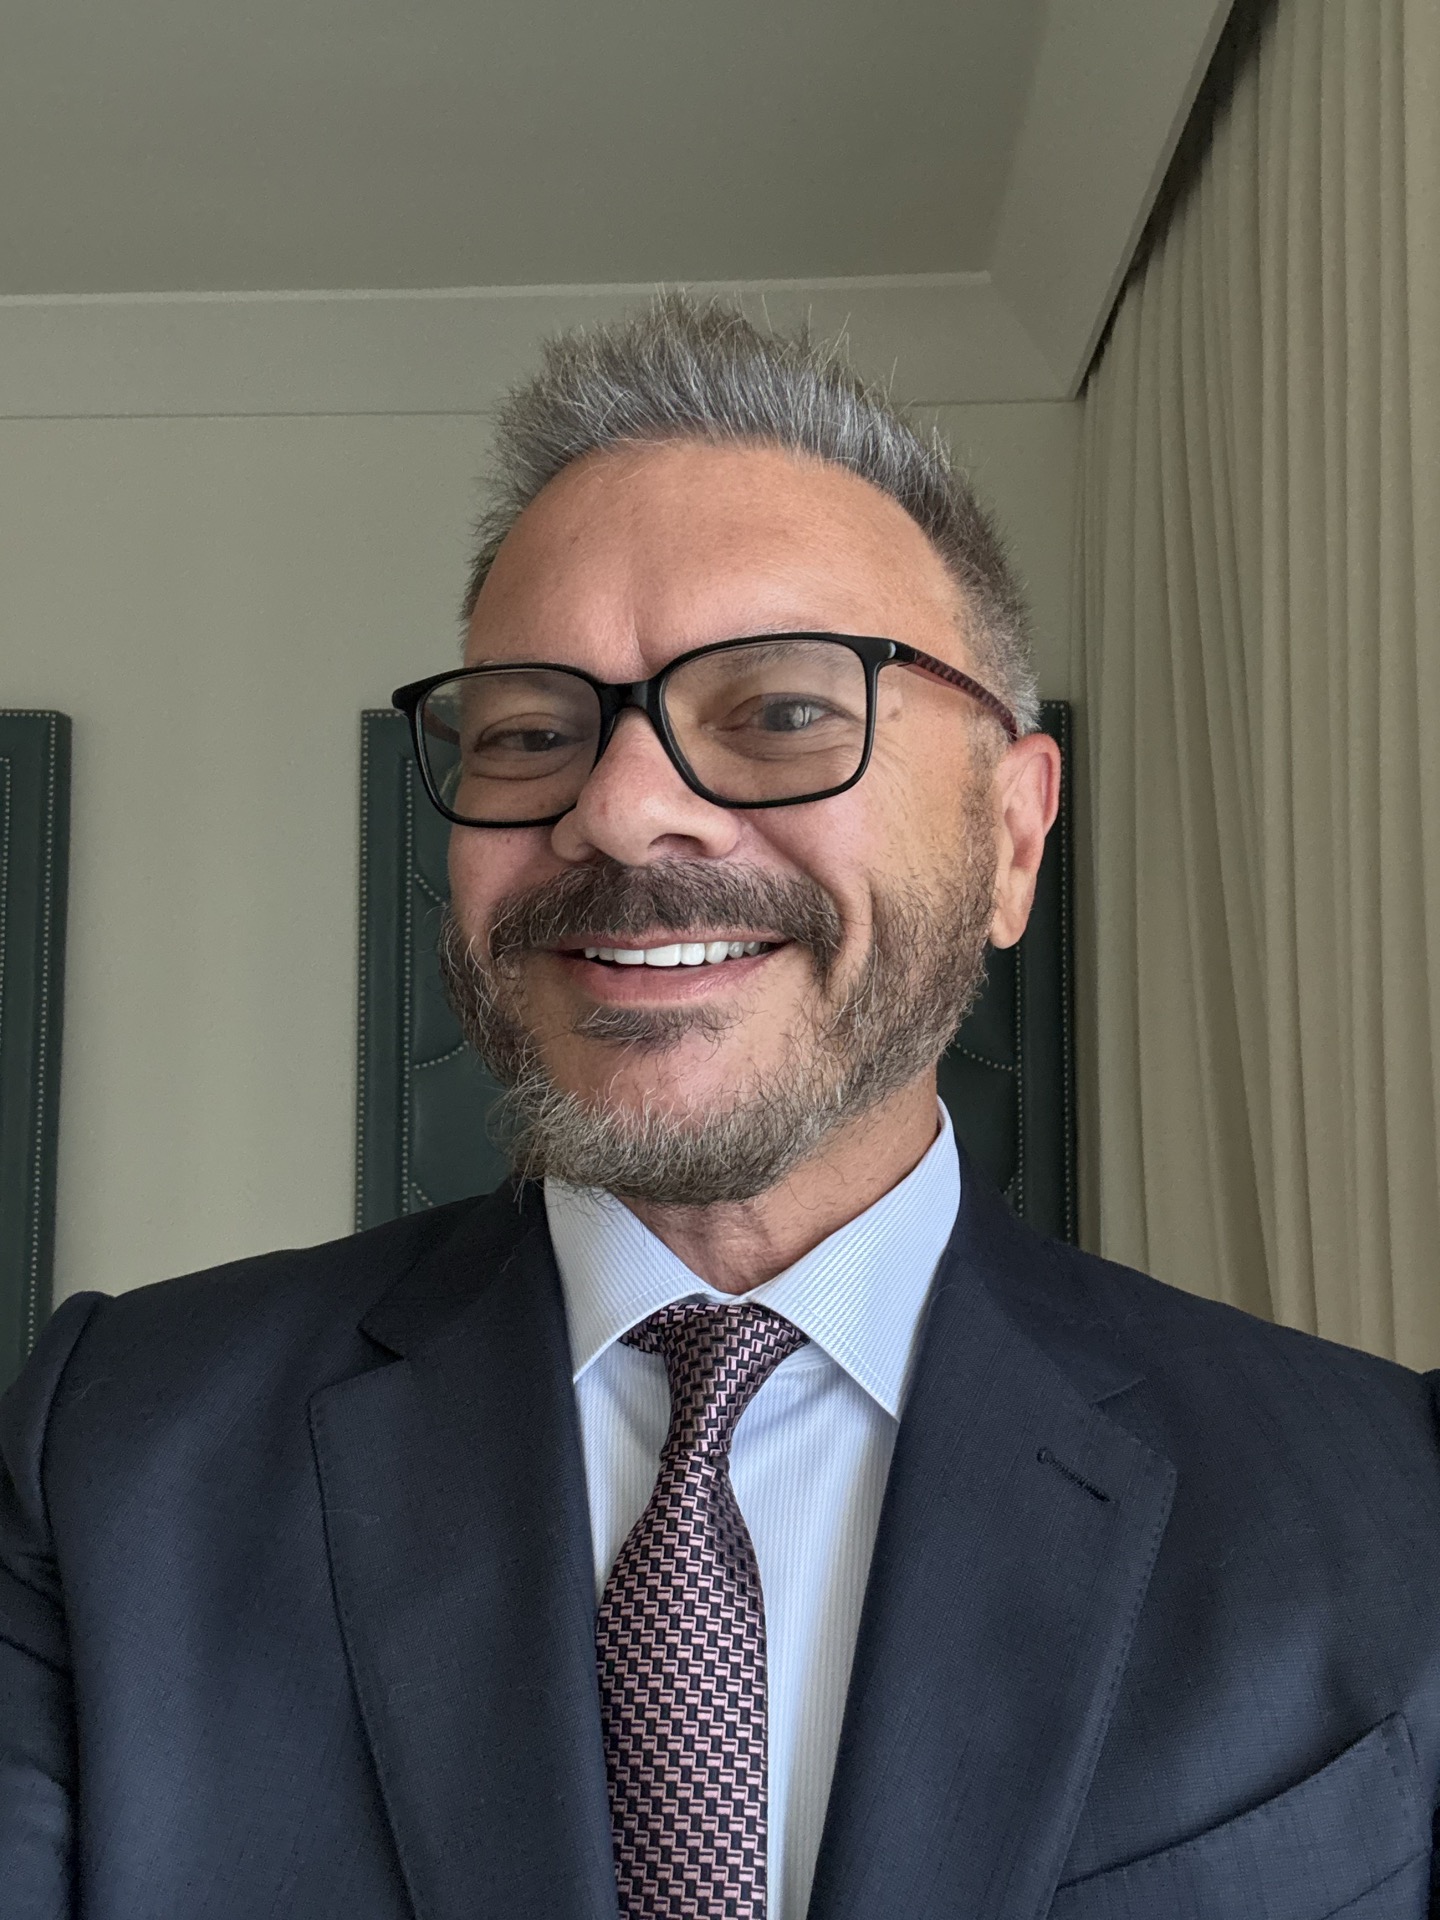
Joe White, principal
Reverse Mortgages of Canada is the reverse mortgage practice of 360 Lending Solutions, led by Joe White.
Joe has spent nearly thirty years in the Canadian mortgage industry. He founded REMIC, the Real Estate and Mortgage Institute of Canada, the country's largest mortgage and insurance education company, and he wrote the Ontario mortgage agent licensing textbook now in its sixteenth edition. If you deal with a licensed mortgage agent in Ontario, there is a good chance they studied from a book he wrote. He was inducted into the Canadian Mortgage Hall of Fame in 2019.
That matters here for one practical reason. Most people arranging reverse mortgages sell one product. We teach the whole subject, including the parts that do not flatter it, which is why you will get a recommendation against this product when it is not the right fit.
At a glance
If you have read this far
See what the numbers actually look like
An estimate is not an argument for or against. It just tells you whether the amounts involved are big enough to be worth the conversation.
How much could you unlock from your home?
A quick estimate of the tax-free cash a reverse mortgage could release, based on the four things that move the number most. It gives you a range, not a promise — the exact figure comes from an appraisal and a conversation.
About the home and the homeowners
Four questions. Nothing here identifies you.
If two people own the home, enter the younger age. Lenders price against whoever is expected to live there longest, so a couple usually qualifies for less than the older partner would alone. It is the most commonly misunderstood part of this product.
Your own estimate is fine at this stage.
Location changes this more than most people expect — the same home can be worth tens of thousands more or less depending only on the community.
$0–$0
What moved your estimate
Get the real number
A licensed agent at 360 Lending Solutions will run your actual address, ages and property details and send you the exact figure.
This is an estimate, not an offer of credit. The figures shown are indicative only, produced from a simplified model, and are not a quote, a pre-approval, or a commitment to lend. Actual amounts depend on a full application, a property appraisal, and the lender's criteria and rates on the day. Amounts are rounded.
Reverse mortgages are available to homeowners aged 55 and over. Interest accrues on the outstanding balance and reduces the equity remaining in the home. Independent legal advice is required before completion.
Still not sure? That is the right place to be
Nobody should decide this from a web page. Call and we will walk through your situation, including the options that are not ours.