Do you qualify for a reverse mortgage?
Qualifying works almost backwards from an ordinary mortgage. Your income barely matters. Your credit score barely matters. Your age and your address matter enormously.
Here is what actually decides it, in the order the lender looks at it.
Not sure whether your property type is acceptable? That is a two-minute phone call and it is worth making before anyone orders an appraisal.
The hard requirements
Four things that are not negotiable
Fail any of these and the answer is no, at every lender, regardless of how much equity you have.
Aged 55 or over, and that means everyone on title
Every registered owner must be at least 55. One owner under 55 stops the application, even if their spouse is 80. And be clear on the mechanic that costs people the most money: where two people own the home, the amount available is set by the younger of them. A couple qualifies for materially less than the older partner would alone. This is the single most misunderstood part of the product.
It has to be your principal residence
The home you actually live in, for most of the year. Not a rental, not a cottage you visit in summer, not a property held for investment. If you later stop living there permanently, the loan becomes repayable, and that includes a permanent move into long-term care.
The property has to be in an area the lender will lend in
Every lender grades communities into lending bands, and they do not agree with each other. A town in one lender's top band can sit two tiers lower at another, which changes the percentage of value they will advance. Some communities are excluded outright by one lender and perfectly acceptable to the next. This is a large part of why using a brokerage matters.
Independent legal advice, before completion
Not optional and not a formality. A lawyer acting for you alone has to review the contract with you and confirm you understood it. Budget for it, and give it the time it deserves.
Property types
What the lenders will and will not take security on
This is where most no answers actually come from, and where two lenders diverge most sharply. General guidance follows; confirm your specific property with us before anything is ordered.
Detached and semi-detached
The straightforward case. Accepted everywhere, in any reasonable community, and attracts the most generous advances.
Townhouses and row houses
Generally fine, freehold or condominium. A freehold town usually prices closer to a detached home than a condominium apartment does.
Condominium apartments
Widely accepted, at a lower advance than a house of the same value. Lenders may look at the corporation's reserve fund and the size of the building. Very small corporations and some older buildings get declined.
Rural property and acreage
Possible and common, with more caution. Well and septic, large lot sizes, outbuildings and anything with a farm or commercial element all narrow the field of lenders and reduce the advance.
Mobile, modular and life lease
Difficult. Mobile homes on leased land are usually a no. Modular homes on owned land are sometimes acceptable. Life lease arrangements are generally not. Ask before you get your hopes up.
Mixed use and unusual titles
A shop with a flat above, a duplex you partly rent out, co-ownership structures. Case by case, and the answer often depends entirely on which lender is asked.
Unusual property? That is the call worth making. Tell us what it is and we will tell you honestly whether any of the lenders we work with will take it, before you spend anything.
Call 1-416-878-9448What does not stop you
Four things people wrongly assume disqualify them
A low income, or no employment income at all
There is no debt service test in the way a conventional mortgage has one, because you are not making payments. Pension income, no income, income that would fail a stress test: none of it stops this. That is precisely the gap this product exists to fill.
An imperfect credit history
Credit is reviewed, but it is not the gate it is on ordinary lending. What lenders care about is whether property taxes and insurance have been kept up, because those protect their security. Old defaults and a modest score are usually survivable.
Having an existing mortgage on the home
Very common and not a barrier, provided there is enough equity. The existing mortgage is discharged out of the advance as part of the transaction. Check the penalty on it first, because that cost lands on your file and occasionally changes the answer.
Being under 65, or in your late 80s
Eligibility runs from 55 with no upper limit. What changes with age is the percentage of value available, which rises as you get older. In your mid fifties the amount is modest and the lenders differ from each other most sharply, so shopping the file matters most at exactly that age.
Qualifying and being well advised are different questions. If you qualify comfortably for a secured line of credit and can service it, that is usually the better answer and we will say so. General background from the regulator that licenses us: FSRA on mortgage brokering.
Who you are dealing with
The people who train the industry on this product
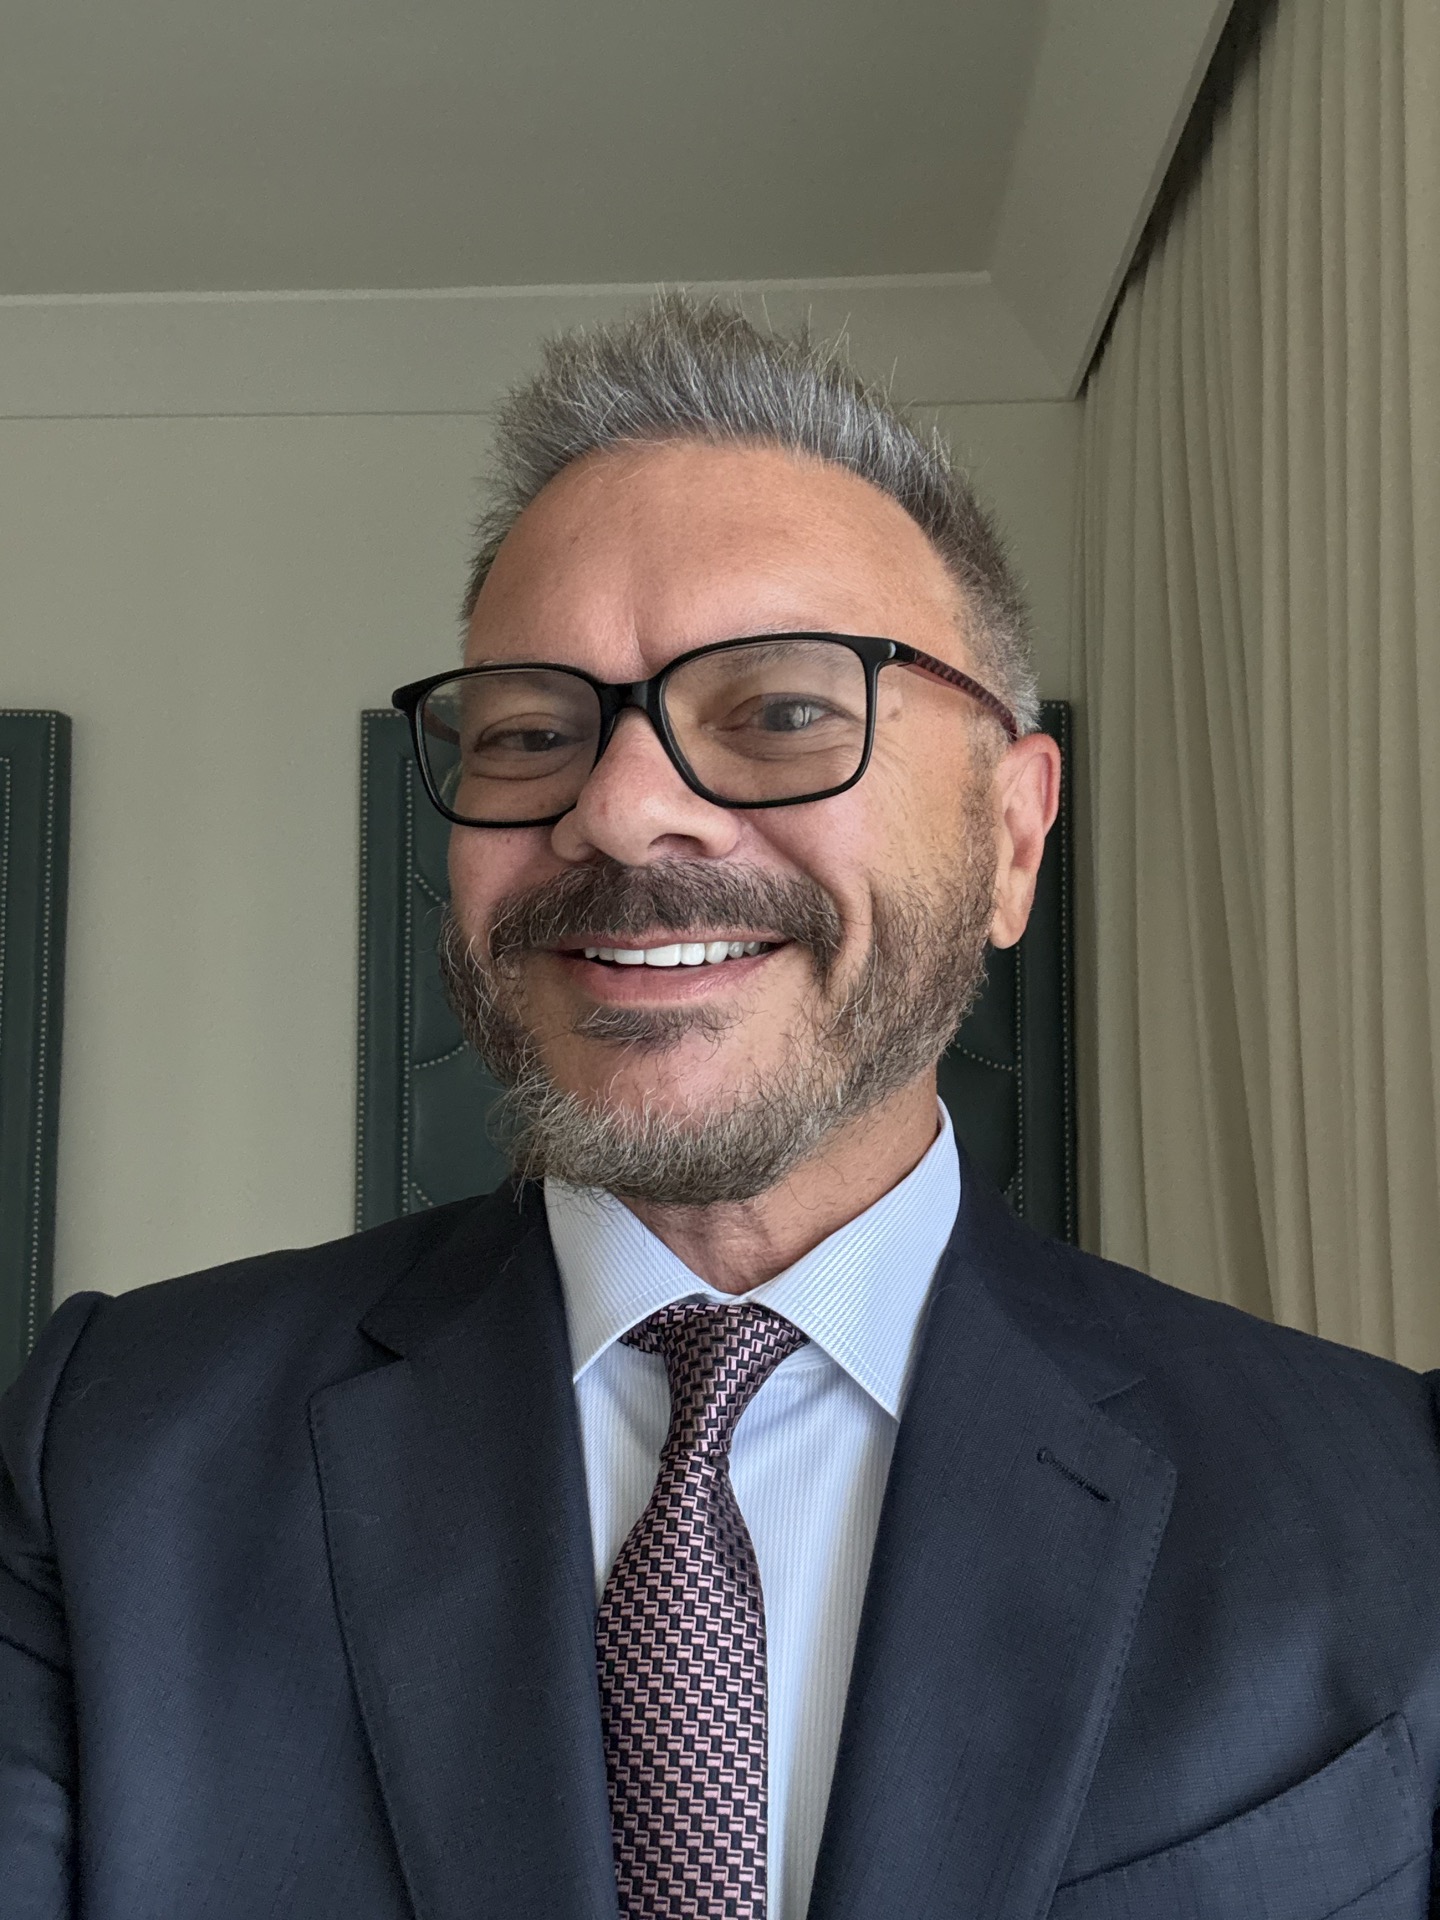
Joe White, principal
Reverse Mortgages of Canada is the reverse mortgage practice of 360 Lending Solutions, led by Joe White.
Joe has spent nearly thirty years in the Canadian mortgage industry. He founded REMIC, the Real Estate and Mortgage Institute of Canada, the country's largest mortgage and insurance education company, and he wrote the Ontario mortgage agent licensing textbook now in its sixteenth edition. If you deal with a licensed mortgage agent in Ontario, there is a good chance they studied from a book he wrote. He was inducted into the Canadian Mortgage Hall of Fame in 2019.
That matters here for one practical reason. Most people arranging reverse mortgages sell one product. We teach the whole subject, including the parts that do not flatter it, which is why you will get a recommendation against this product when it is not the right fit.
At a glance
How much could you unlock from your home?
A quick estimate of the tax-free cash a reverse mortgage could release, based on the four things that move the number most. It gives you a range, not a promise — the exact figure comes from an appraisal and a conversation.
About the home and the homeowners
Four questions. Nothing here identifies you.
If two people own the home, enter the younger age. Lenders price against whoever is expected to live there longest, so a couple usually qualifies for less than the older partner would alone. It is the most commonly misunderstood part of this product.
Your own estimate is fine at this stage.
Location changes this more than most people expect — the same home can be worth tens of thousands more or less depending only on the community.
$0–$0
What moved your estimate
Get the real number
A licensed agent at 360 Lending Solutions will run your actual address, ages and property details and send you the exact figure.
This is an estimate, not an offer of credit. The figures shown are indicative only, produced from a simplified model, and are not a quote, a pre-approval, or a commitment to lend. Actual amounts depend on a full application, a property appraisal, and the lender's criteria and rates on the day. Amounts are rounded.
Reverse mortgages are available to homeowners aged 55 and over. Interest accrues on the outstanding balance and reduces the equity remaining in the home. Independent legal advice is required before completion.
Find out in one phone call, not one appraisal
Tell us the ages, the property type and the community. We will tell you whether it qualifies, roughly what is available, and whether we think it is worth doing.