Reverse mortgages in Ontario: how much can you take out of your home?
If you are 55 or older and own your home in Ontario, a reverse mortgage releases part of its value as tax-free cash. No monthly payments. You keep the title to your home.
Get an estimate in under a minute below. Then talk to someone who will tell you plainly whether it is a good idea in your situation, including when it is not.
Prefer to talk it through? Most people do. There is no application and no obligation in a phone call.
Start here
Two very different questions, depending on who is asking
Roughly half the people who reach a page like this are not the homeowner. They are a son or daughter, an accountant, or a financial planner, trying to work out whether this is sensible for someone they care about. The honest answers are different, so the two paths are separate.
I own the home
You are 55 or older, you own your home in Ontario, and you want to know what is actually available and what it costs.
- An estimate of the range you could access
- What it costs and how the interest works
- What happens to the house, and when
I am advising someone else
You are a son or daughter, an accountant, or a licensed advisor, and you want to know whether this is a good idea for your parent or client before anyone signs anything.
- When a reverse mortgage is the wrong answer
- Effect on OAS, GIS and taxable income
- What it does to the estate
How much could you unlock from your home?
A quick estimate of the tax-free cash a reverse mortgage could release, based on the four things that move the number most. It gives you a range, not a promise — the exact figure comes from an appraisal and a conversation.
About the home and the homeowners
Four questions. Nothing here identifies you.
If two people own the home, enter the younger age. Lenders price against whoever is expected to live there longest, so a couple usually qualifies for less than the older partner would alone. It is the most commonly misunderstood part of this product.
Your own estimate is fine at this stage.
Any mortgage, secured line of credit or home equity loan registered against the property. These have to be cleared out of the advance, so what reaches you is the difference. Leave at zero if the home is free and clear. Check whether your current lender charges a penalty for paying out early, because that lands on your file too.
If the property is unusual, say so here rather than rounding to the nearest option. It changes which lenders will look at it, and on some of them the answer is none.
Lenders grade communities into bands, and the bands do not agree with each other. Your postal code sets the band below.
Location moves this more than most people expect. The same home can be worth tens of thousands more or less depending only on the community, so if our reading looks wrong to you, change it. You live there and we do not.
$0–$0
After clearing your existing debt
$0–$0
What moved your estimate
Get the real number
A licensed agent at 360 Lending Solutions will run your actual address, ages and property details and send you the exact figure.
Only if you want the exact figure rather than a range. The street tells us which lending band the property sits in, which is the difference between an estimate and a number. We do not order anything or contact anyone without your say-so.
This is an estimate, not an offer of credit. The figures shown are indicative only, produced from a simplified model, and are not a quote, a pre-approval, or a commitment to lend. Actual amounts depend on a full application, a property appraisal, and the lender's criteria and rates on the day. Amounts are rounded.
Reverse mortgages are available to homeowners aged 55 and over. Interest accrues on the outstanding balance and reduces the equity remaining in the home. Independent legal advice is required before completion.
The four questions everyone asks
The things people are actually worried about
These come up in nearly every conversation. Two of them are misunderstandings. One is a real drawback you should weigh carefully before proceeding.
Can the lender take my home?
No. You keep the title. The lender registers a charge against the property in the same way a bank does with an ordinary mortgage. Nobody takes ownership from you.
What you agree to is straightforward: keep the home as your principal residence, keep the property taxes and insurance paid, and keep the place in reasonable repair. Meet those and the loan is not called. It becomes repayable when the last homeowner sells, moves out permanently, or passes away.
Will there be anything left for my children?
Usually yes, and this is the question that worries families most. You are borrowing a portion of your home's value, not all of it, and the rest of the equity remains yours.
Reverse mortgages in Canada generally carry a guarantee that the estate will never owe more than the fair market value of the home at the time it is sold, provided the terms have been met. In practice that means the debt cannot be passed to your children. It is worth confirming that guarantee appears in the specific contract in front of you, and we will show you where.
Isn't the interest rate high?
Yes. It is higher than a conventional mortgage, and that is a genuine cost you should take seriously. You are not making payments, so interest compounds onto the balance and the equity in your home shrinks over time rather than growing.
The rate is higher because the lender waits, sometimes fifteen or twenty years, without receiving a payment. Whether that trade is worth making depends on your alternatives. If you can comfortably qualify for a conventional mortgage or a secured line of credit and afford the payments, that is usually cheaper and we will tell you so. A reverse mortgage earns its place when the payments on those options are the problem.
Is this a scam?
It is a regulated mortgage product offered by Canadian lenders and arranged through brokerages licensed by the Financial Services Regulatory Authority of Ontario. Our licence number is 12448 and you can verify it on FSRA's public register.
There is also a protection built into the process: you are required to get independent legal advice before completion. A lawyer who acts for neither the lender nor us has to sit with you, explain the contract, and confirm you understood it. That requirement exists precisely because this product is aimed at older homeowners.
For advisors, accountants and family
If you are the one being asked whether this is a good idea
You are not looking for a sales pitch. You want to know where this product fits, where it does not, and what it does to the rest of the plan. Here is the short version.
It does not affect OAS or GIS
The proceeds are loan advances, not income. They are not taxable and they do not enter net income for income-tested benefits. For a client near an OAS clawback threshold, that distinction is often the whole reason this option is on the table rather than a RRIF withdrawal.
The younger age drives everything
Where two people own the home, the amount available is set by the younger of them, not the older. A couple qualifies for less than the older partner would alone. This is the most commonly misunderstood mechanic of the product, and it surprises people at the worst moment.
Location moves the number more than value does
Lenders price by lending area, not by postal code. The same home, at the same value and the same age, can attract a materially different advance depending only on the community it sits in. Two towns twenty minutes apart can differ by tens of thousands of dollars.
When we will tell you it is the wrong answer
If the client can service a conventional mortgage or a secured line of credit, that is usually cheaper. If the need is short term and the home is likely to sell within a couple of years, the setup costs rarely justify it. If a family member is pressuring an elderly owner to release cash, we stop and involve the lawyer early.
Have a client scenario you want a straight answer on? Send us the ages, the property type and the community, and we will tell you what is realistically available and whether we think it is the right move. No client contact unless you ask for it.
Call 1-416-878-9448Who you are dealing with
The people who train the industry on this product
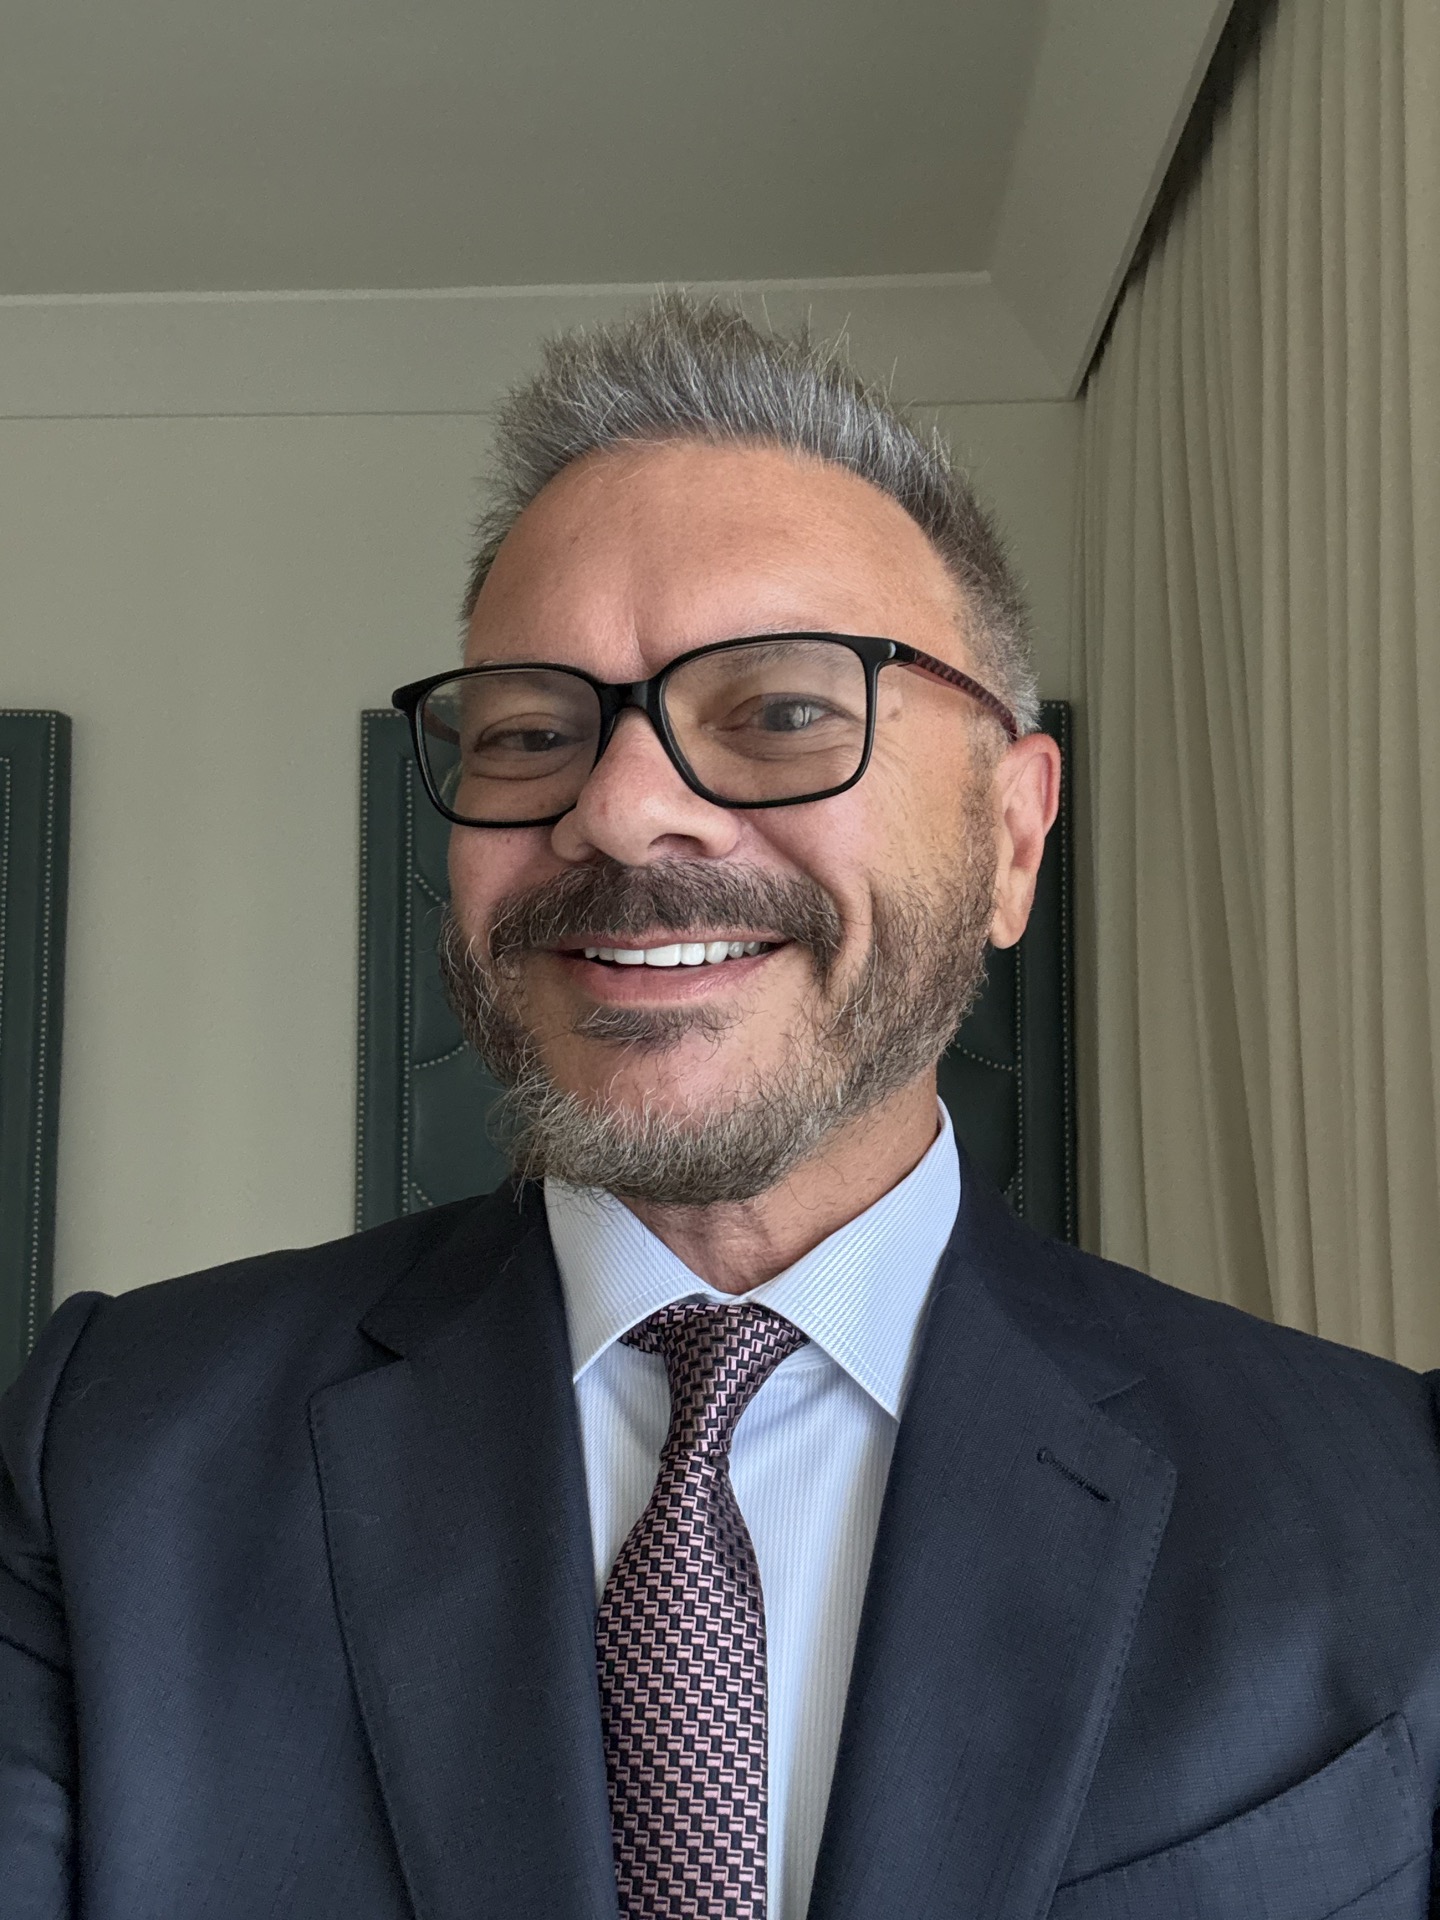
Joe White, principal
Reverse Mortgages of Canada is the reverse mortgage practice of 360 Lending Solutions, led by Joe White.
Joe has spent nearly thirty years in the Canadian mortgage industry. He founded REMIC, the Real Estate and Mortgage Institute of Canada, the country's largest mortgage and insurance education company, and he wrote the Ontario mortgage agent licensing textbook now in its sixteenth edition. If you deal with a licensed mortgage agent in Ontario, there is a good chance they studied from a book he wrote. He was inducted into the Canadian Mortgage Hall of Fame in 2019.
That matters here for one practical reason. Most people arranging reverse mortgages sell one product. We teach the whole subject, including the parts that do not flatter it, which is why you will get a recommendation against this product when it is not the right fit.
At a glance
The people you will actually deal with
Not a call centre. A small Ontario brokerage where the person who answers the phone is the person who works on your file.
