Call one lender and you get one answer
There is more than one reverse mortgage lender in Canada, and they do not value homes the same way, lend in the same places, or charge the same penalty to get out early. A lender can only offer you its own product. We are not restricted that way.
This page explains how we decide which one suits a given situation, and what we check before we place anything.
No cost to you for the comparison. We are paid by the lender when a file closes.
Why it matters which one
The same house, the same owners, two different offers
People assume a reverse mortgage is a reverse mortgage and the only question is the rate. It is not the only question, and often it is not even the important one.
Lenders draw their maps differently
Every lender grades communities into lending bands, and the bands do not match each other. A town that sits in one lender's top band can sit two tiers lower at another, which changes the percentage of value they will advance. We have seen towns an hour outside Toronto where the two are far apart on the same property. Nobody calling a single lender ever finds this out.
Age moves the two apart
Every lender advances more as the borrowers get older, but they do not do it at the same rate. Around 70 the offers can land close to each other. In the mid fifties, at the young end of eligibility, the gap between lenders widens sharply. If you are 55, which lender you are placed with is the single biggest factor in the amount available to you.
The exit terms are where the real money is
The rate gets the attention. The prepayment penalty decides what it actually costs, because most of these loans end early, on a sale or a move into care. Two lenders with a similar rate can be thousands apart on the way out. That difference does not appear on any comparison chart.
How we match you
What actually decides the recommendation
Not a preferred lender, not whoever pays the most. These are the things that change the answer, and they are the questions we ask on a first call.
Lump sum or income
Some people need one large advance to clear a mortgage or a debt. Others want a smaller amount now and regular top-ups over the years, which keeps interest off money you have not spent yet. Not every lender does both well, and the scheduled advance option is worth real money to the right borrower.
Your age, and both ages if there are two of you
The younger borrower usually governs. At the young end of eligibility the lenders separate the most, so this is where shopping the file matters most. Later on, the differences narrow and other terms start to matter more than the amount.
Where the home is
Property type and community drive the advance as much as age does. A detached home in a large centre, a condominium, a rural property on a well and septic and a small town all get treated differently, and differently again by each lender.
How long you plan to stay
If the plan is to stay for life, the compounding and the estate guarantee matter most. If a move is plausible within five years, the penalty structure and portability matter more than the rate. These point at different lenders.
What happens if care is needed
Lenders differ on how they treat a move into long-term care, particularly when one spouse moves and one stays. For a couple in their eighties this is often the deciding term, and it is the one almost nobody asks about until it is happening.
How much equity you want protected
If leaving the maximum to the estate is the priority, the largest available advance is the wrong target. Sometimes the right recommendation is a smaller amount from a different lender, and sometimes it is not this product at all.
Advising a parent or a client? Give us the ages, the property type and the community and we will tell you which way the lenders break on that file and why. No client contact unless you ask for it.
Call 1-416-878-9448The checklist
What we read before we place a file
The parts of a commitment that decide what this costs you, in the order they tend to bite.
How the prepayment penalty is calculated
Not the headline number. The method, the declining schedule if there is one, and the circumstances that waive it. Most reverse mortgages end before the term does, so this is the term most likely to cost you money.
Whether scheduled advances are available, and what they cost
Taking money as you need it instead of all at once can save a great deal of interest over a long hold. The option is not universal and the terms attached to it vary.
Portability, deferral and the care provisions
Can the loan move with you to a new home. What happens when one borrower moves into care and the other stays. How long the estate has to settle. These are contract terms, not marketing points, and they are not the same at every lender.
The negative equity guarantee, in the actual document
Reverse mortgages in Canada generally guarantee the estate will never owe more than the fair market value of the home at sale, provided the terms have been met. We show you the clause rather than assert it. Conditions attach to it, and you should read them.
Appraisal, legal and setup costs, and who absorbs them
These are small next to the loan and large next to each other. Some are negotiable. Some get covered in a promotion. It is worth knowing which before the paperwork starts.
Whether the lender will lend on this property at all
Rural acreage, mixed use, mobile and modular homes, life leases, some condominium corporations. Plenty of properties are a straightforward yes at one lender and a flat no at another. Finding that out before an appraisal is ordered saves money and a fortnight.
Being straight with you
How we get paid, and what we will not do
The lender pays us, not you
We are compensated by the lender when a file funds. You should know that, and you should know it creates an incentive to place business. It is also why the page before this one opens by explaining when a reverse mortgage is the wrong answer, and why we tell people to take a line of credit instead when they qualify for one. That page is here.
We work with the lenders we are approved with, and we say so
We do not claim access to every product in the country. We will tell you plainly which lenders we can place a file with, and if the right answer for you sits somewhere we cannot reach, we will say that too.
You get the reasoning, not just the recommendation
When we recommend one lender over another you will be told which terms drove it and what you are giving up by not taking the other. If the deciding factor is a penalty clause you would not have read, that is exactly the part you should hear about.
Independent legal advice, every time
You will get your own lawyer, separate from ours, and they will go through the contract with you before you sign. That is a requirement on these products, not a courtesy, and it exists for good reason. We build the timeline around it rather than against it.
Independent background reading, from sources that are not selling you anything: the Financial Consumer Agency of Canada on reverse mortgages, and FSRA, the regulator that licenses us, on dealing with a mortgage brokerage in Ontario.
Who you are dealing with
The people who train the industry on this product
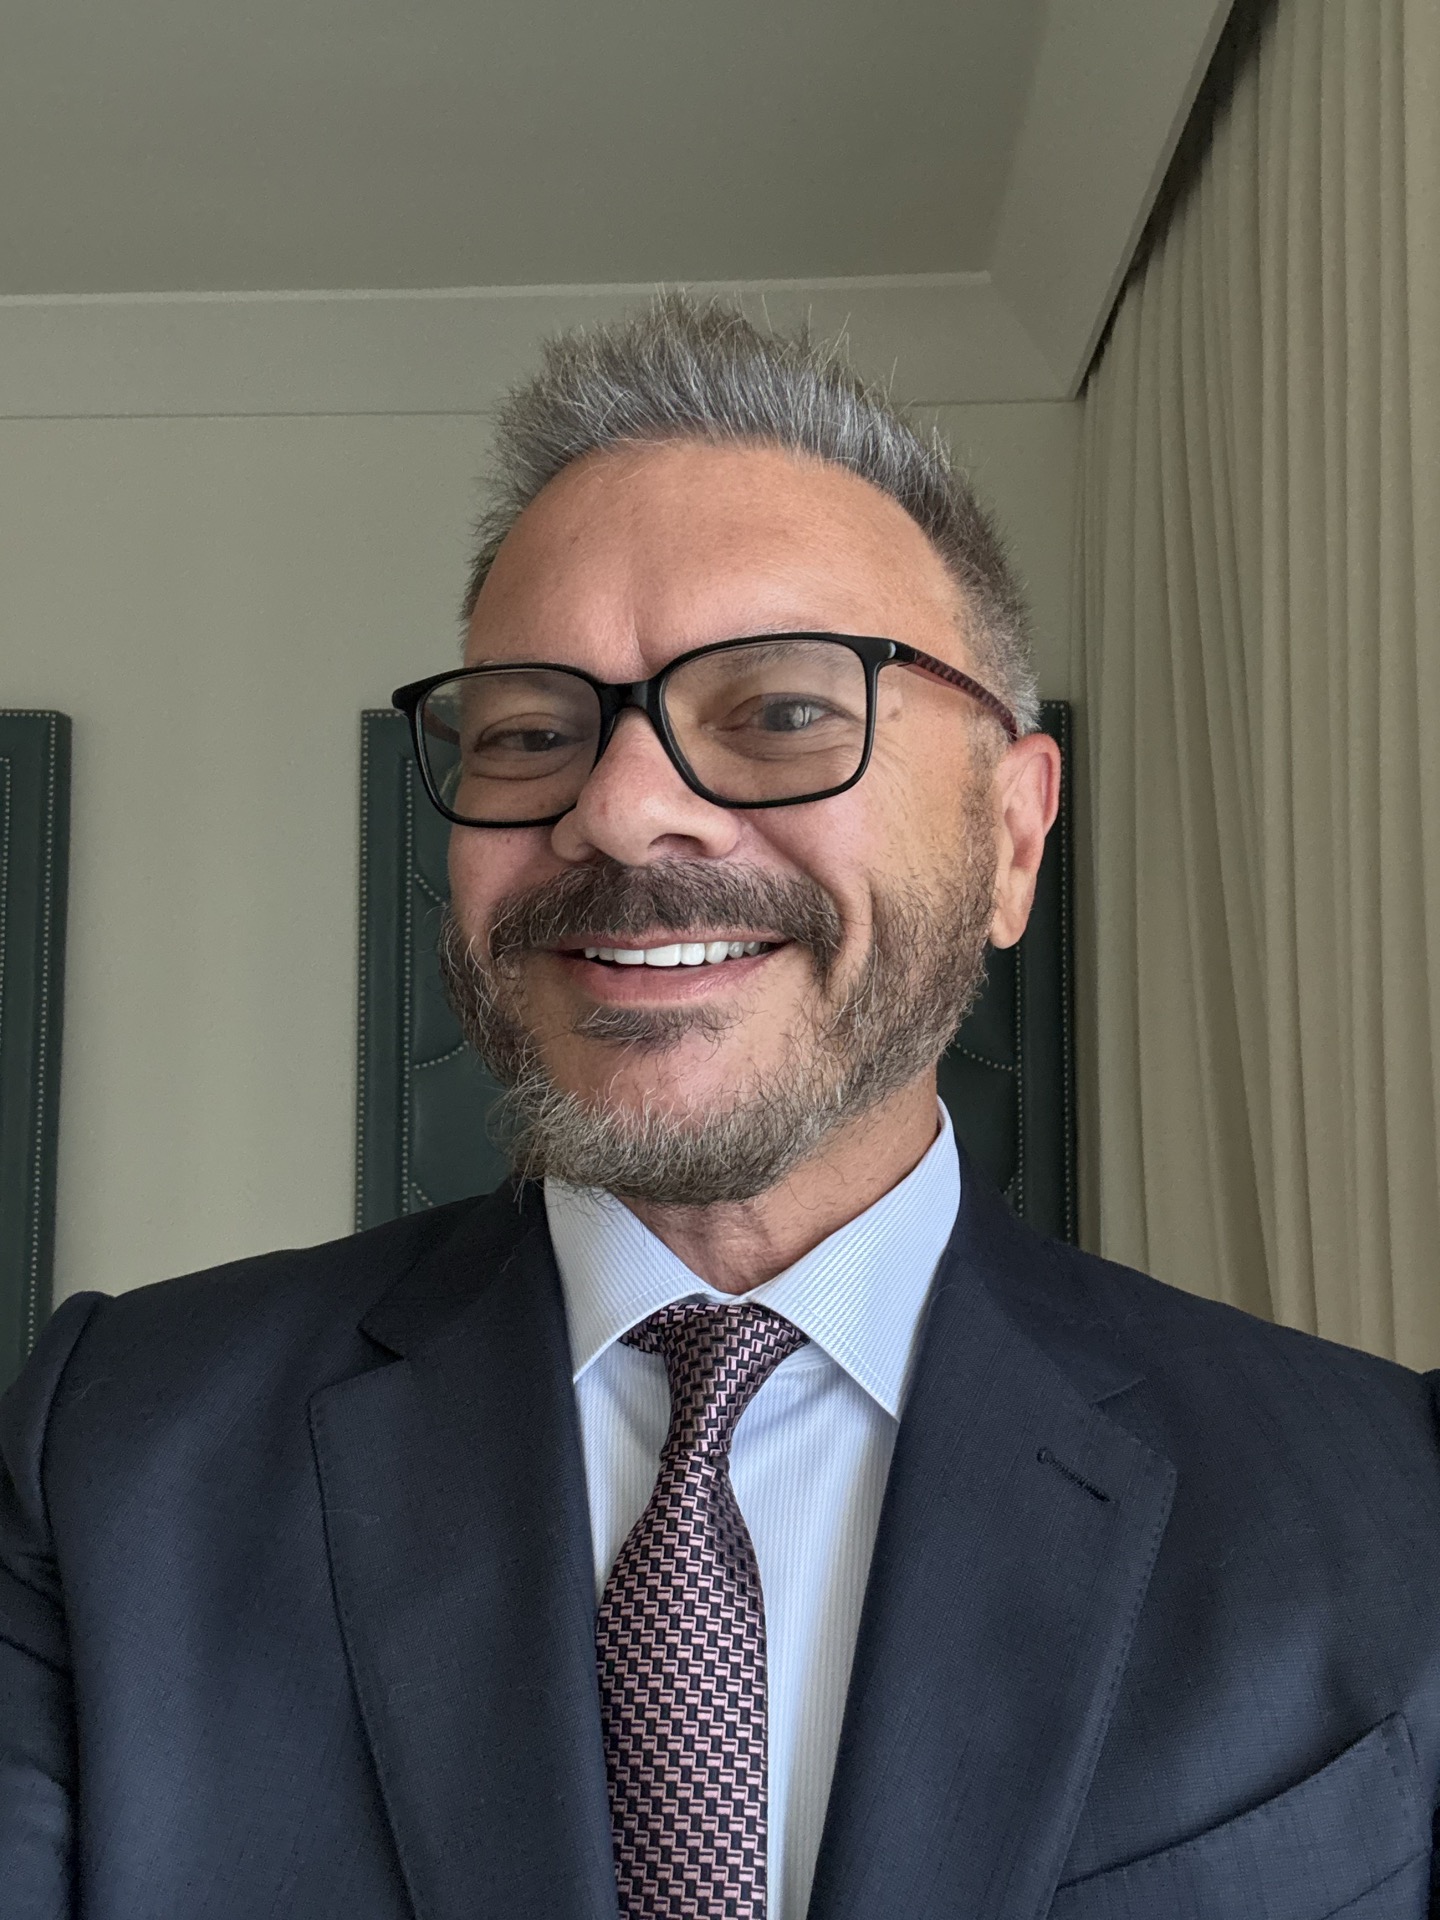
Joe White, principal
Reverse Mortgages of Canada is the reverse mortgage practice of 360 Lending Solutions, led by Joe White.
Joe has spent nearly thirty years in the Canadian mortgage industry. He founded REMIC, the Real Estate and Mortgage Institute of Canada, the country's largest mortgage and insurance education company, and he wrote the Ontario mortgage agent licensing textbook now in its sixteenth edition. If you deal with a licensed mortgage agent in Ontario, there is a good chance they studied from a book he wrote. He was inducted into the Canadian Mortgage Hall of Fame in 2019.
That matters here for one practical reason. Most people arranging reverse mortgages sell one product. We teach the whole subject, including the parts that do not flatter it, which is why you will get a recommendation against this product when it is not the right fit.
At a glance
A starting point
See the range before you pick anybody
The estimate below is deliberately coarse and it is not tied to any one lender. It tells you whether the amounts are large enough to be worth a conversation. Which lender, and how much more one might advance than another, is what the conversation is for.
How much could you unlock from your home?
A quick estimate of the tax-free cash a reverse mortgage could release, based on the four things that move the number most. It gives you a range, not a promise — the exact figure comes from an appraisal and a conversation.
About the home and the homeowners
Four questions. Nothing here identifies you.
If two people own the home, enter the younger age. Lenders price against whoever is expected to live there longest, so a couple usually qualifies for less than the older partner would alone. It is the most commonly misunderstood part of this product.
Your own estimate is fine at this stage.
Location changes this more than most people expect — the same home can be worth tens of thousands more or less depending only on the community.
$0–$0
What moved your estimate
Get the real number
A licensed agent at 360 Lending Solutions will run your actual address, ages and property details and send you the exact figure.
This is an estimate, not an offer of credit. The figures shown are indicative only, produced from a simplified model, and are not a quote, a pre-approval, or a commitment to lend. Actual amounts depend on a full application, a property appraisal, and the lender's criteria and rates on the day. Amounts are rounded.
Reverse mortgages are available to homeowners aged 55 and over. Interest accrues on the outstanding balance and reduces the equity remaining in the home. Independent legal advice is required before completion.
Let us shop it before you commit to anyone
Tell us the ages, the property and the community. We will tell you how the lenders break on that file, which one we would recommend, and why. It is a phone call, not an application.