The people who train the industry on this product
Most people arranging reverse mortgages sell one product from one lender. We wrote the textbook the agents study from.
That is not a boast about competence so much as an explanation of why this site tells you when not to do it.
Who you are dealing with
The people who train the industry on this product
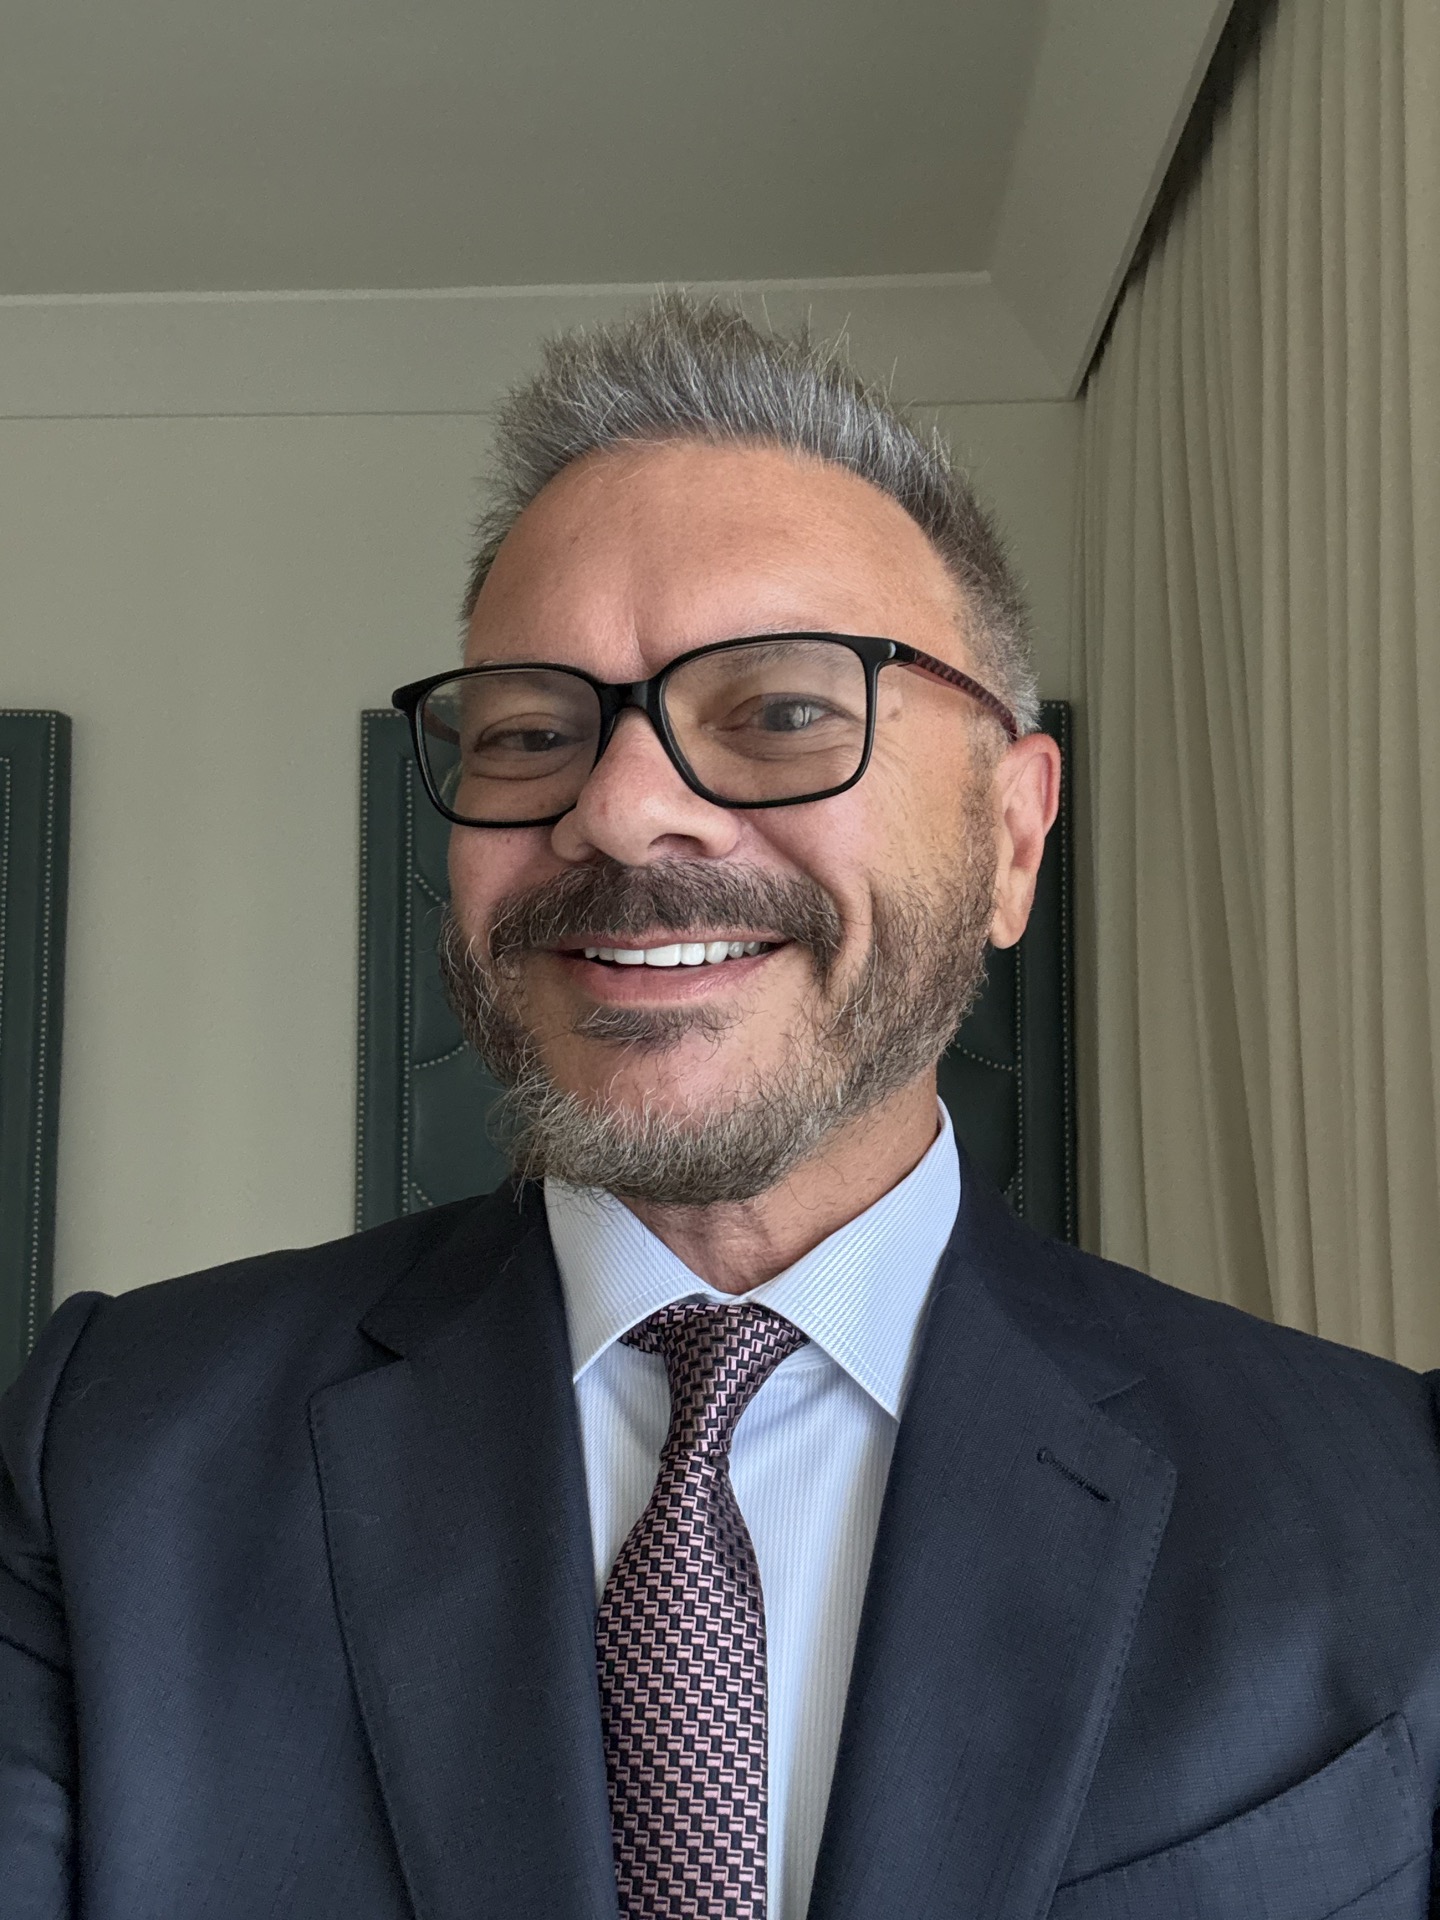
Joe White, principal
Reverse Mortgages of Canada is the reverse mortgage practice of 360 Lending Solutions, led by Joe White.
Joe has spent nearly thirty years in the Canadian mortgage industry. He founded REMIC, the Real Estate and Mortgage Institute of Canada, the country's largest mortgage and insurance education company, and he wrote the Ontario mortgage agent licensing textbook now in its sixteenth edition. If you deal with a licensed mortgage agent in Ontario, there is a good chance they studied from a book he wrote. He was inducted into the Canadian Mortgage Hall of Fame in 2019.
That matters here for one practical reason. Most people arranging reverse mortgages sell one product. We teach the whole subject, including the parts that do not flatter it, which is why you will get a recommendation against this product when it is not the right fit.
At a glance
Who you are dealing with, precisely
The registration details, in full
Anyone arranging a mortgage in Ontario must be licensed, and you are entitled to check. Here is everything you need to do that.
The licensed entity
Reverse Mortgages of Canada is a registered trade name of 360 Lending Solutions, a mortgage brokerage licensed by the Financial Services Regulatory Authority of Ontario under Brokerage Licence #12448. The full registered name on FSRA's public register is 2402303 Ontario Corp. operating as 360 Lending Solutions - Mortgage Architects.
Verify licence #12448 on FSRA's public register. Do it. It takes ten seconds and you should do it with anyone who asks you about your house.
Where we are, and where we work
2175 Sheppard Avenue East, Suite 307, Toronto, Ontario, M2J 1W8. We deal in mortgages in Ontario only. Mortgage brokering is provincially regulated, and we would rather work in one province properly than four badly. If you are outside Ontario we will tell you so on the first call rather than the third.
How we are paid
The lender pays us when a file funds. You pay us nothing. If that ever differed on a particular file it would be disclosed to you in writing before you signed anything. The full cost breakdown is here, including the incentive our compensation model creates and why you should weigh our advice knowing about it.
If something goes wrong
We have a published complaints process, with names, timelines and the escalation route to the regulator. It is here. A brokerage that makes you hunt for that is telling you something.
How we work
Four commitments, which you may hold us to
We will tell you not to do it
If you can service a secured line of credit or a conventional mortgage, that is cheaper and we will say so, even though we earn nothing by saying it. Roughly a third of the conversations we have end this way.
We compare lenders, and show you the reasoning
Not just the rate. The prepayment structure, the care provisions, the lending band your community sits in. You will be told which terms drove the recommendation and what you give up by not taking the other. How that works.
We slow down when someone else is asking
If an adult child, a caregiver or anyone else is pushing an older homeowner to release cash, we involve the lawyer early and we talk to the homeowner alone. That is not a judgement about your family. It is the most common way this product gets misused.
You deal with a person, not a queue
A small Ontario brokerage. The person who answers the phone is the person who works on your file, and they will still be there when you call back in March with a question.
Advisors, accountants and planners: send us a client scenario and we will give you a straight read on it, including when the answer is that this is the wrong product. No client contact unless you ask for it.
Call 1-416-878-9448Start with a conversation, not an application
Call and we will work through your situation, tell you what is realistically available, and tell you plainly whether we think you should do it.