How much can you get from a reverse mortgage in Ontario?
Four questions, an estimate in under a minute, and no obligation. No monthly payments. You keep the title to your home.
Rather skip the form? Call and we will work it out with you on the phone.
How much could you unlock from your home?
A quick estimate of the tax-free cash a reverse mortgage could release, based on the four things that move the number most. It gives you a range, not a promise — the exact figure comes from an appraisal and a conversation.
About the home and the homeowners
Four questions. Nothing here identifies you.
If two people own the home, enter the younger age. Lenders price against whoever is expected to live there longest, so a couple usually qualifies for less than the older partner would alone. It is the most commonly misunderstood part of this product.
Your own estimate is fine at this stage.
Any mortgage, secured line of credit or home equity loan registered against the property. These have to be cleared out of the advance, so what reaches you is the difference. Leave at zero if the home is free and clear. Check whether your current lender charges a penalty for paying out early, because that lands on your file too.
If the property is unusual, say so here rather than rounding to the nearest option. It changes which lenders will look at it, and on some of them the answer is none.
Lenders grade communities into bands, and the bands do not agree with each other. Your postal code sets the band below.
Location moves this more than most people expect. The same home can be worth tens of thousands more or less depending only on the community, so if our reading looks wrong to you, change it. You live there and we do not.
$0–$0
After clearing your existing debt
$0–$0
What moved your estimate
Get the real number
A licensed agent at 360 Lending Solutions will run your actual address, ages and property details and send you the exact figure.
Only if you want the exact figure rather than a range. The street tells us which lending band the property sits in, which is the difference between an estimate and a number. We do not order anything or contact anyone without your say-so.
This is an estimate, not an offer of credit. The figures shown are indicative only, produced from a simplified model, and are not a quote, a pre-approval, or a commitment to lend. Actual amounts depend on a full application, a property appraisal, and the lender's criteria and rates on the day. Amounts are rounded.
Reverse mortgages are available to homeowners aged 55 and over. Interest accrues on the outstanding balance and reduces the equity remaining in the home. Independent legal advice is required before completion.
Before you go further
Two things worth knowing before you take that number seriously
Will there be anything left for my children?
Usually yes. You are borrowing a portion of your home's value, not all of it, and the rest of the equity remains yours. Reverse mortgages in Canada generally carry a guarantee that the estate will never owe more than the fair market value of the home when it is sold, provided the terms have been met, which means the debt cannot be passed to your children.
Isn't the interest rate high?
Yes, higher than a conventional mortgage, and that is a real cost. You make no payments, so interest compounds onto the balance and your equity shrinks over time rather than growing. If you can comfortably qualify for a conventional mortgage or a secured line of credit and afford the payments, that is usually cheaper and we will tell you so.
Who you are dealing with
The people who train the industry on this product
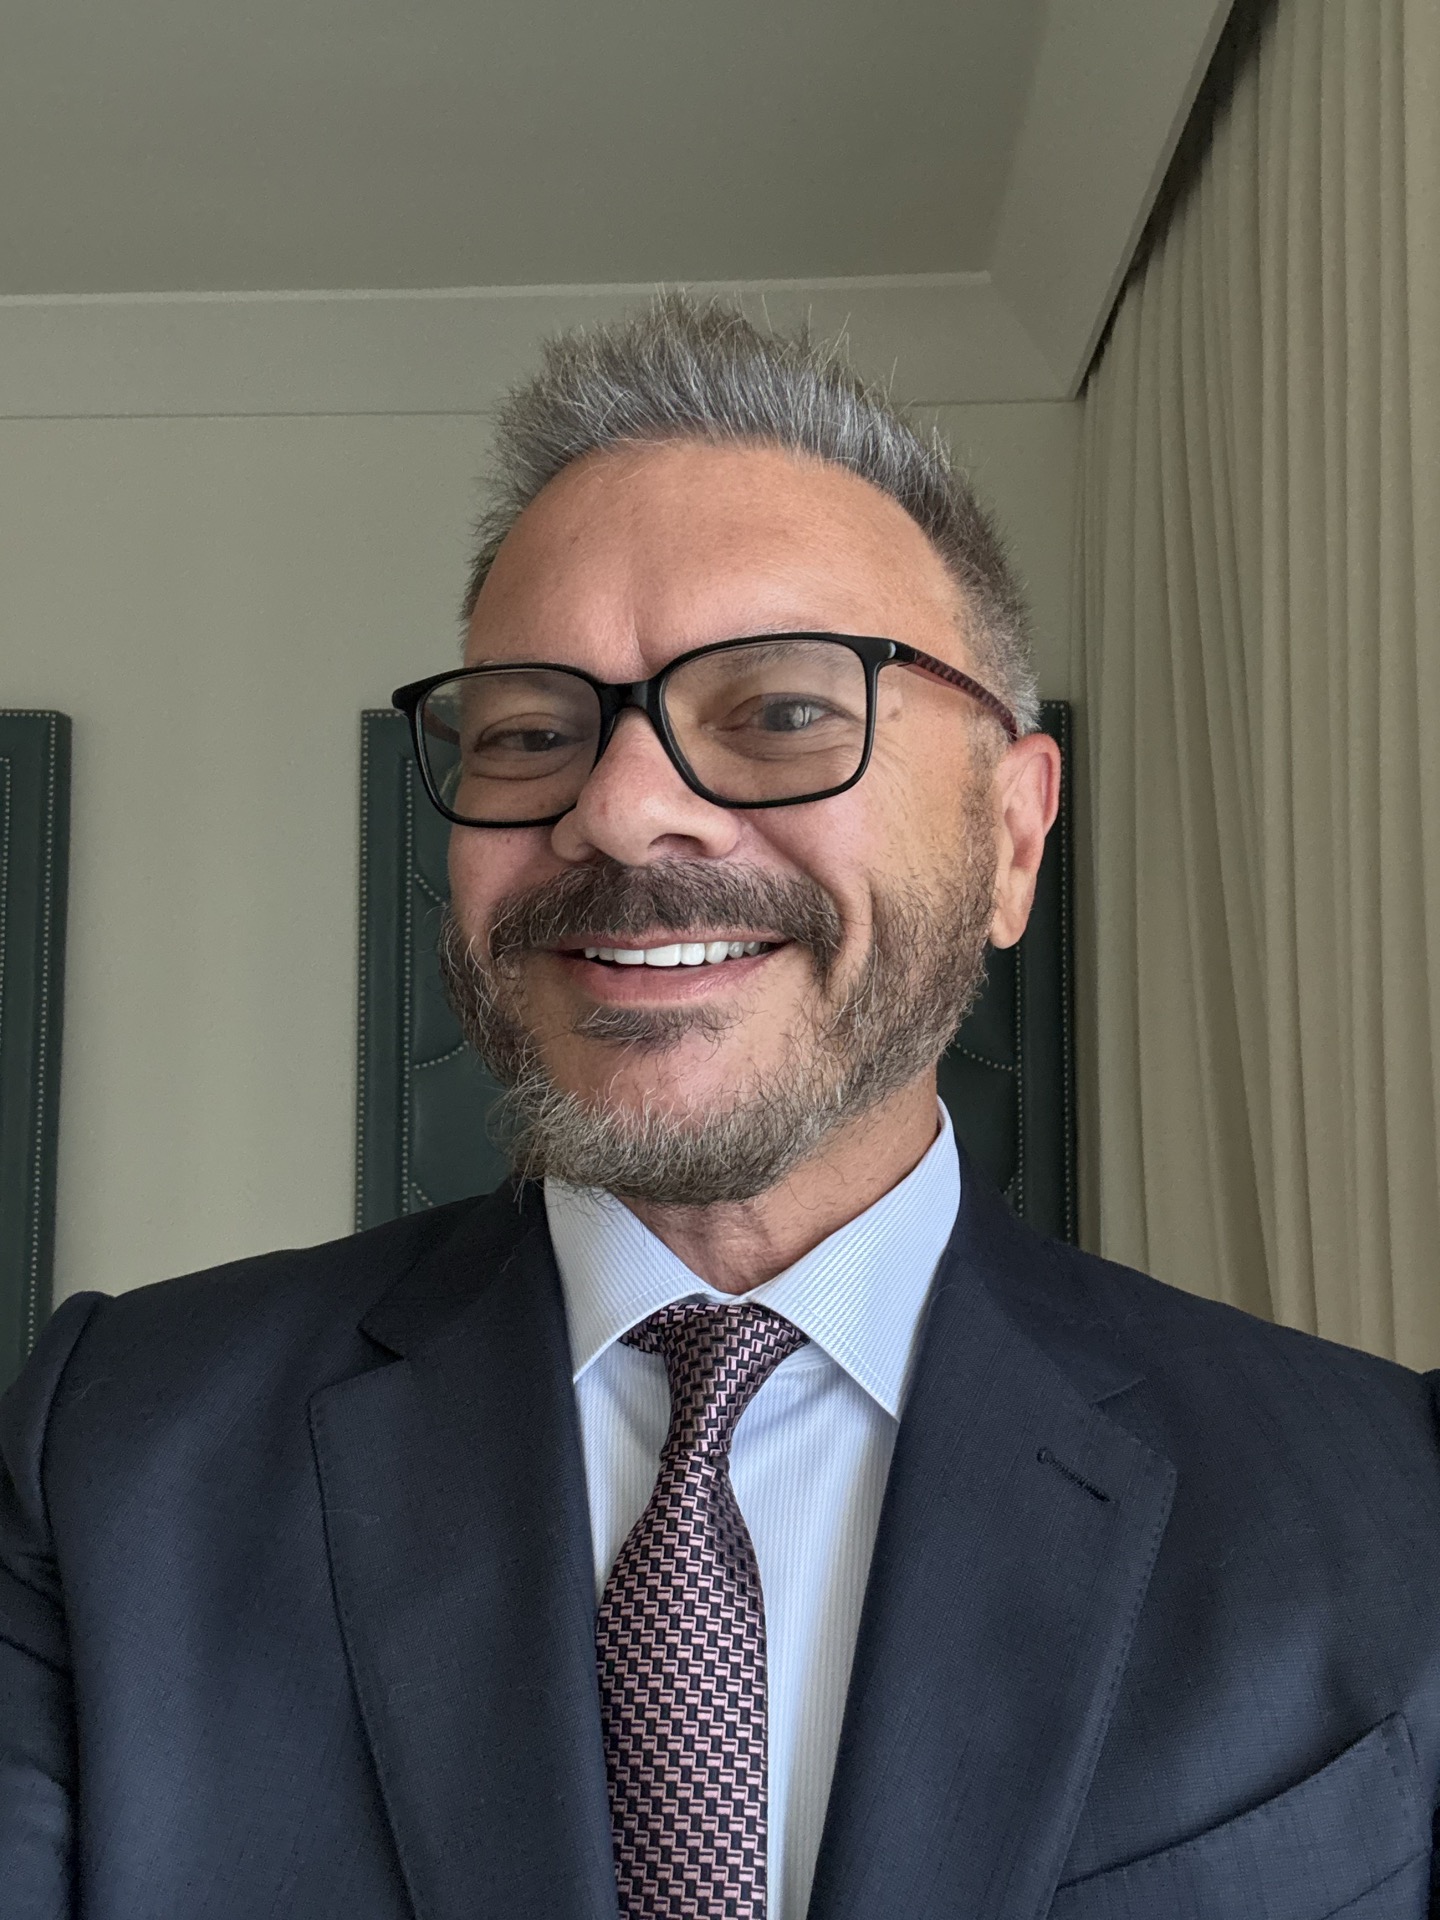
Joe White, principal
Reverse Mortgages of Canada is the reverse mortgage practice of 360 Lending Solutions, led by Joe White.
Joe has spent nearly thirty years in the Canadian mortgage industry. He founded REMIC, the Real Estate and Mortgage Institute of Canada, the country's largest mortgage and insurance education company, and he wrote the Ontario mortgage agent licensing textbook now in its sixteenth edition. If you deal with a licensed mortgage agent in Ontario, there is a good chance they studied from a book he wrote. He was inducted into the Canadian Mortgage Hall of Fame in 2019.
That matters here for one practical reason. Most people arranging reverse mortgages sell one product. We teach the whole subject, including the parts that do not flatter it, which is why you will get a recommendation against this product when it is not the right fit.
At a glance
Get the exact figure, not the estimate
The number above comes from a simplified model. The real one comes from your address, your ages and an appraisal. That is a short conversation, not an application.